If you’re thinking about buying a home in Charlotte, you’ve probably checked mortgage rates online — and maybe the number you saw made you question whether now is the right time to buy.
But here’s something many buyers don’t realize:
The mortgage rate you see online isn’t necessarily the mortgage rate you’ll get.
The rates you see in headlines, social media posts, and online averages are useful for understanding the overall market. But your actual mortgage rate depends on your specific financial situation, the loan you choose, and the lender evaluating your application.
What Determines Your Actual Mortgage Rate?
There isn’t one universal mortgage rate for every buyer.
According to the Consumer Financial Protection Bureau (CFPB), factors such as your credit profile, down payment, loan type, and loan term can affect the mortgage rate and borrowing costs available to you.
Some of the biggest factors include:
Your credit score. Generally, stronger credit can help you qualify for more favorable loan terms.
Your down payment. The amount you put down affects how much you need to finance and your loan-to-value ratio (LTV). A larger down payment may also help you access different loan terms.
Your existing debt and finances. Lenders evaluate your overall financial picture when determining what you can qualify for.
Your loan program. Conventional, FHA, VA, USDA, and other mortgage programs have different requirements and cost structures.
Your loan term. A 15-year mortgage and a 30-year mortgage, for example, may come with different rates and monthly payments.
That’s why seeing a mortgage rate online doesn’t tell you exactly what buying a home will cost you.
There May Be More Options Than the Headline Rate Suggests
The interest rate itself is only one part of the equation.
Depending on the home, financing, and transaction, buyers may also be able to explore strategies such as mortgage rate buydowns or seller concessions.
A mortgage rate buydown involves paying an upfront cost to reduce the interest rate. Depending on the transaction, that cost may sometimes be negotiated with a seller or builder.
Seller concessions may help cover eligible closing costs, depending on the loan program and terms of the transaction.
This is one reason buyers shouldn’t make their entire homebuying decision based on a rate they saw in a headline.
The better question is:
What would buying a home look like based on my actual numbers?
Pre-Qualification vs. Pre-Approval: What’s the Difference?
If you’re seriously considering buying a home in Charlotte, getting pre-approved can give you a much clearer picture of your purchasing power.
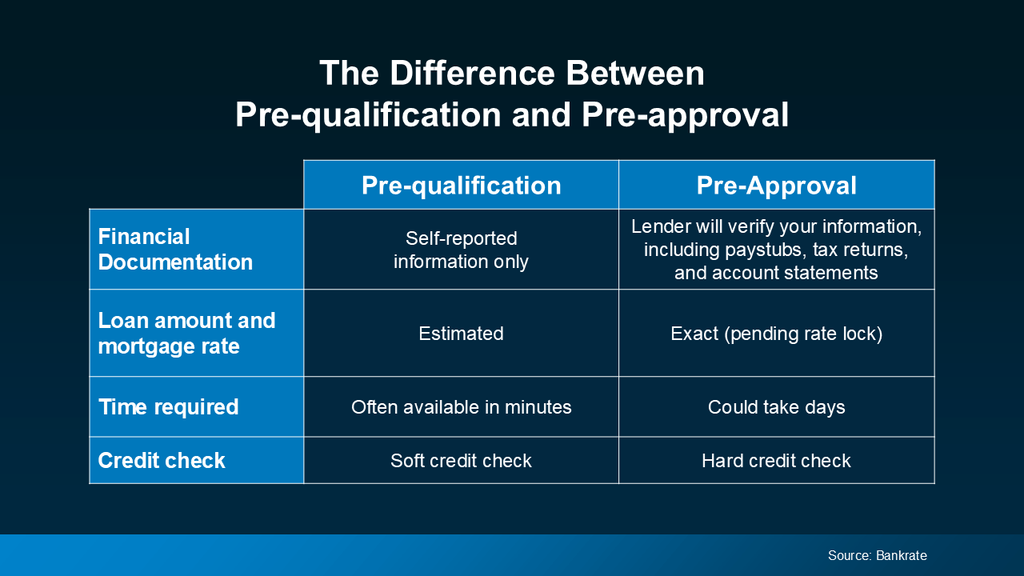
A pre-qualification is generally an initial estimate based largely on financial information you provide.
A pre-approval goes further. The lender reviews and verifies financial information to determine how much you may be able to borrow, subject to the lender’s conditions and final loan approval.
For someone actively preparing to buy, that information can be far more useful than relying on national mortgage-rate averages.
Should You Wait for Mortgage Rates To Drop Before Buying?
There isn’t one answer that works for every buyer.
Instead of trying to perfectly time mortgage rates, consider asking your lender:
- What rate and loan programs could I qualify for today?
- What would my estimated monthly payment be?
- Would waiting 3, 6, or 12 months materially change my financial position?
- Are there strategies available to reduce my upfront costs or monthly payment?
- How would different down payment amounts affect my options?
Then look at those numbers alongside home prices, available inventory, your personal finances, and your plans.
You may discover that buying now makes sense for your situation.
Or you may decide that preparing for a few more months is the better move.
Either way, you’re making that decision based on your numbers — not a headline.
Thinking About Buying a Home in Charlotte, NC?
Your first step doesn’t have to be touring houses.
It can simply be understanding what your options actually look like.
A trusted lender can help you understand your financing and potential mortgage rate. And an experienced local real estate agent can help you understand what those numbers mean when you start looking at homes in Charlotte and the surrounding areas.
Enrique Alzate helps buyers navigate the Charlotte, North Carolina real estate market with a clear strategy based on their goals, budget, and current market conditions.
If you’re considering buying a home in Charlotte, reach out to Enrique Alzate to start exploring your options.
Enrique Alzate
📞 (980) 322-3272
Mortgage rates, loan eligibility, and financing terms vary by borrower and lender. A licensed mortgage professional can provide information specific to your financial situation.